Macquarie Bank has agreed to pay a proposed A$14 million civil penalty after admitting that the way it promoted the "Welcome Rate" on its Macquarie Savings Account between December 2021 and September 2022 broke the law. The corporate regulator ASIC says the offer was described as a "welcome variable rate" and a "bonus", so many savers thought it sat on top of the standard rate. In practice it replaced the standard rate for four months. Macquarie has already paid A$8.8 million in compensation to nearly 40,000 customers, and the penalty still needs a judge's approval.[1][2][3]
 | |
| Bank | Macquarie Bank Limited |
|---|---|
| Regulator | Australian Securities and Investments Commission (ASIC) |
| Court | Supreme Court of New South Wales |
| Product | Macquarie Savings Account, Welcome Rate offer |
| Wording period | December 2021 to September 2022 |
| Promo length | Four months for new customers |
| Admission | Failed to provide financial services efficiently, honestly and fairly (Corporations Act) |
| Proposed penalty | A$14 million, subject to court approval |
| Compensation | A$8.8 million, nearly 40,000 customers |
| Announced | November 11, 2026 (AEDT) |
What happened with the Macquarie Welcome Rate
New customers who opened a Macquarie Savings Account were offered a Welcome Rate for their first four months. On its website, Macquarie called this a "welcome variable rate" and a "bonus". ASIC alleged that language could lead people to believe the extra interest was paid on top of the account's standard variable rate.[2][3]
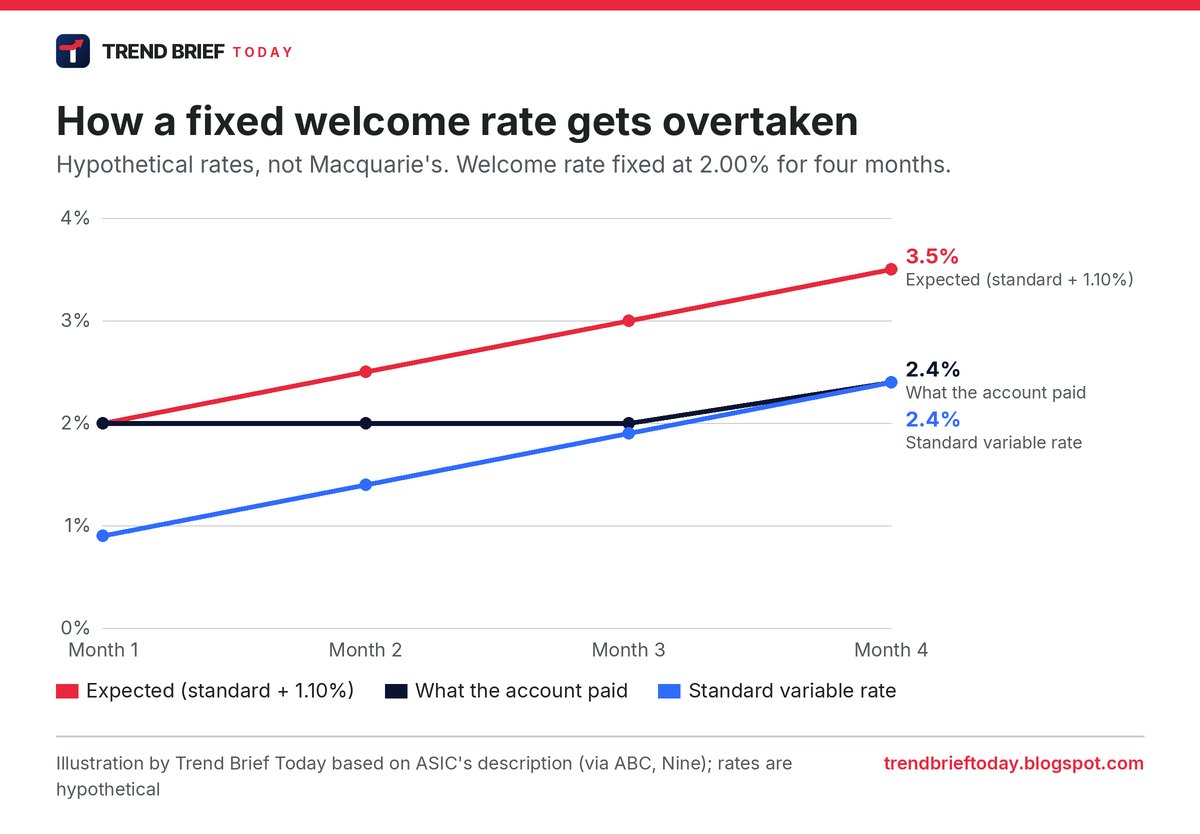
That is not how it worked. According to the regulator, the Welcome Rate generally behaved like a fixed rate that applied instead of the standard rate during the promotional period, not in addition to it.[2][4] Nine.com.au, reporting ASIC's statement, said the starting gap between the two rates was 1.1 percentage points a year.[4]
The timing made the problem bigger. The wording covers December 2021 to September 2022, which is when Australian interest rates began to climb. As the standard variable rate rose, the gap to the fixed Welcome Rate shrank. Once the standard rate went past the Welcome Rate, customers were paid the standard rate and nothing more, even though some expected a bonus margin above it.[1][5]
Is it a fine? The A$14 million penalty explained
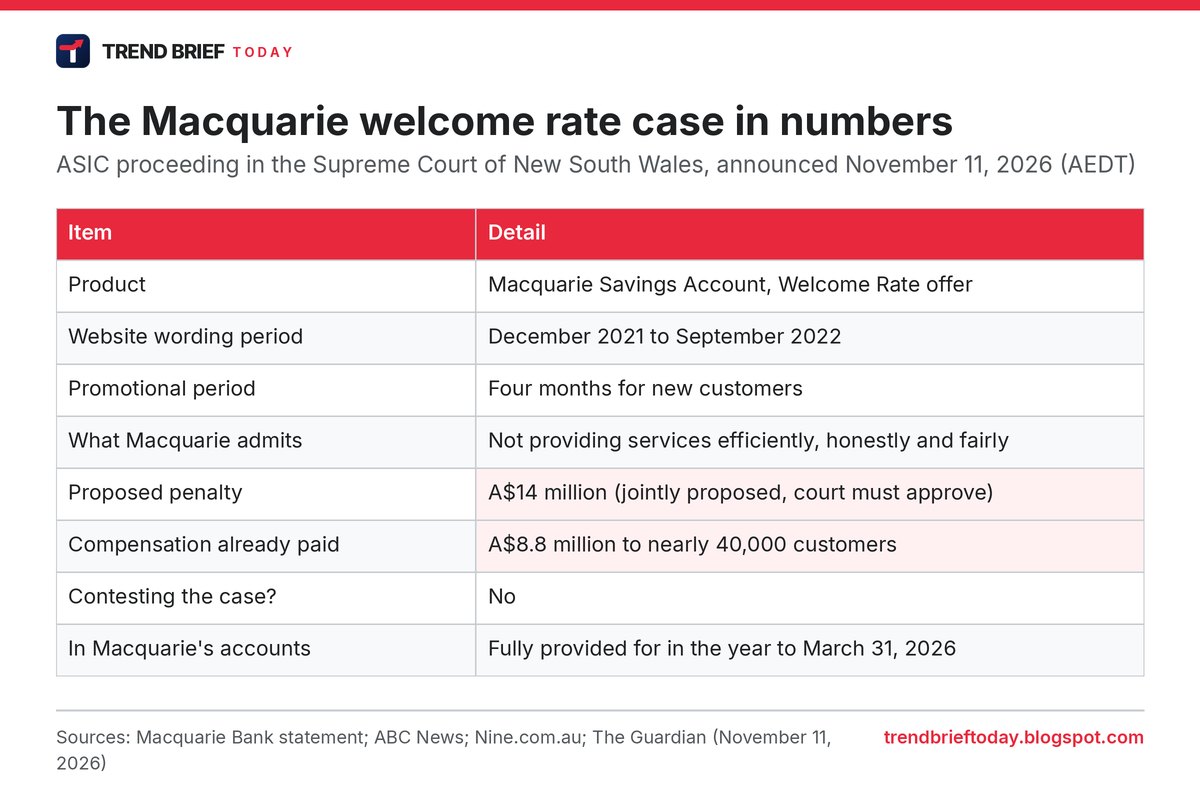
ASIC took the case to the Supreme Court of New South Wales. Macquarie says it will admit that it contravened its obligation to provide financial services "efficiently, honestly and fairly", that it will not fight the case, and that it expects to pay a A$14 million civil penalty.[1][2]
Headlines are calling it a fine, but strictly speaking nothing is final yet. The penalty is a figure the bank and the regulator have jointly put to the court, and the court has to approve it.[2][6] Agreed penalties are usually accepted, but a judge can disagree. We will update this page when there is a ruling.
Macquarie also says the matter was "identified and fully accounted for" in its financial year that ended on March 31, 2026, so the penalty should not come as a fresh hit to its earnings.[1]
Who gets money back: the A$8.8 million remediation
The penalty is separate from compensation. Before ASIC announced the case, Macquarie had already decided to pay A$8.8 million to customers. The ABC reports this has been paid to nearly 40,000 people.[2][7]
Macquarie's head of banking and financial services, Ben Perham, said the payments were designed "to put customers in the position that they would have been if the Welcome Rate was a fixed bonus interest margin." In other words, affected customers were paid as if the Welcome Rate really had been a bonus on top of the standard rate.[1][2]
Neither Macquarie nor the reports we checked describe a new claims process for customers who think they were missed. If you opened a Macquarie Savings Account in that window and are unsure whether you were included, the simplest step is to ask Macquarie directly and keep a record of its answer.
How much could a saver have missed? A worked example
Macquarie has not published the actual rates or a typical payout, so we built a simple example to show how the mechanism works. The numbers below are hypothetical. They use the 1.1 percentage point starting gap that Nine reported, a A$50,000 balance and a standard rate that rises by half a point a month, roughly the pace of 2022's rate rises.
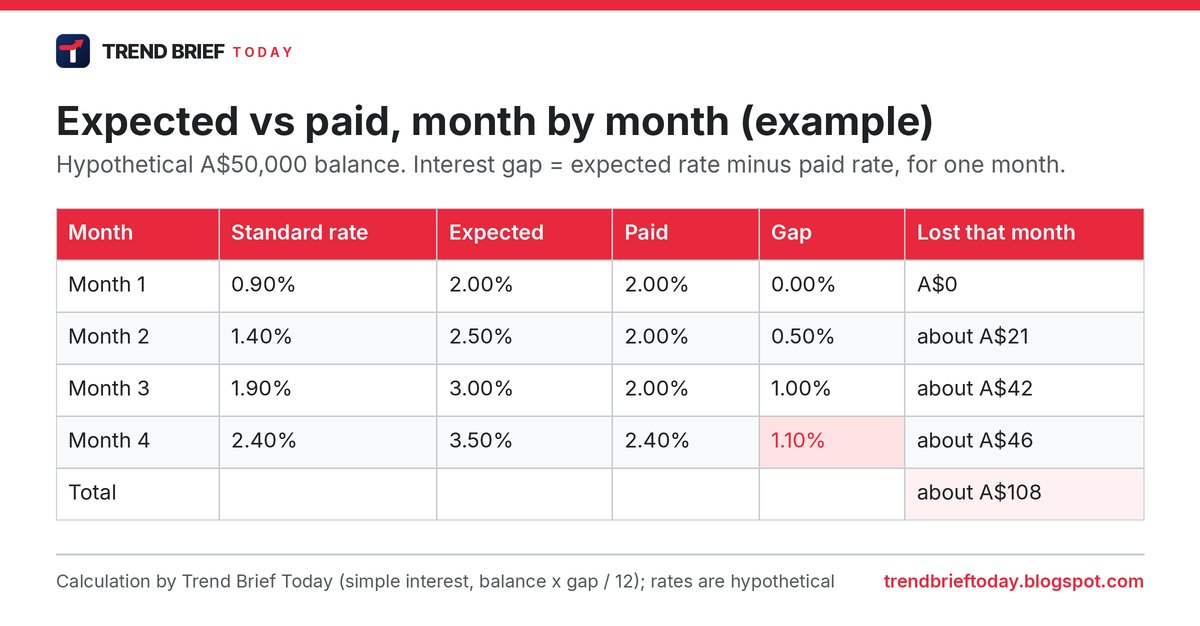
Across four months, our example saver earns about A$108 less than they expected. Average A$8.8 million across nearly 40,000 customers and you get roughly A$220 each, but that is only an average. Real amounts depended on each person's balance and when they joined, so some people will have received far more and some far less.
What ASIC said
ASIC commissioner Alan Kirkland said this was more than a drafting error. "This wasn't just unclear wording. Macquarie's systems and controls were not rigorous enough to identify the risk that customers would misunderstand how the Welcome Rate worked," he said.[2][6]
He also used the case to send a wider message. Australians hold almost A$1.8 trillion in household deposits, and Kirkland said the conditions attached to higher savings rates can be hard to understand. "Higher advertised rates may only apply for a limited time or may depend on the customer meeting certain conditions," he said. "Consumers should check what conditions apply, whether they are meeting them and whether their bank is paying the interest rate they have been promised."[2][8]
The Guardian reports the case comes amid a broader ASIC crackdown on complex savings conditions.[6] It is not a small issue. The ACCC found in a 2023 study that 71% of bonus interest accounts failed to earn the bonus rate each month, and Canstar analysis cited by Yahoo Finance found 41% of savers miss out on bonus interest every month because of hard-to-meet conditions.[6][8]
What Macquarie said
Macquarie accepts that some of the wording on its website "was not sufficiently clear and may have caused confusion". Perham said ASIC had acknowledged the bank's actions were not deliberate, "we should have better explained on our website how the Welcome Rate would be applied and we apologise for any confusion caused."[1][2]
The bank says it has reviewed every product description it uses for transaction and savings accounts and has tightened how customer-facing material is created, approved and published. It says ASIC acknowledged it had "engaged constructively" during the investigation.[1]
How to check your own savings rate
You do not need to be a Macquarie customer for this to matter. With the Reserve Bank's cash rate at 4.85%, an 18-year high, the gap between a good and a poor savings rate is worth real money.[6] Our guide to Westpac's consumer sentiment survey shows how much pressure higher rates are putting on household budgets. These are general steps, not financial advice:
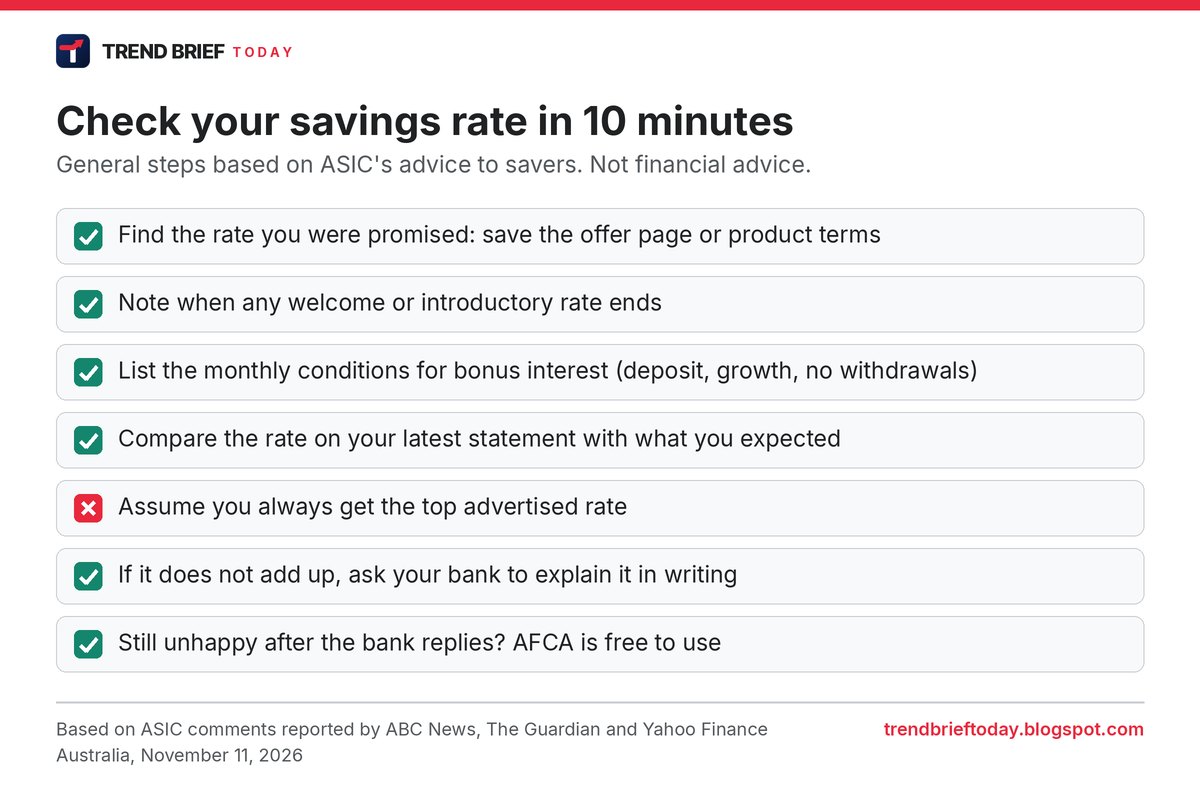
- Know what you signed up for. Save the offer page or product terms when you open an account. Websites change, and a screenshot is the easiest proof of what was promised.
- Mark the end date. Welcome and introductory rates expire. Put the date in your calendar so the drop to the standard rate does not surprise you.
- Read the bonus conditions every month. Many bonus accounts require a minimum deposit, a growing balance or no withdrawals. Missing one condition can cost you the bonus for that month.[6]
- Check the statement, not the ad. Your statement or app shows the rate you were actually paid. Compare it with what you expected.
- Ask, then escalate. Kirkland's advice is to contact your bank if you cannot work out the rate, and to raise it if you met the conditions but did not get the higher rate.[8] If the bank's answer does not resolve it, the Australian Financial Complaints Authority (AFCA) is the free external complaints service for banking disputes.
Timeline
| Date | Event |
|---|---|
| December 2021 | Start of the period covered by the website wording about the Welcome Rate[1] |
| 2022 | Interest rates rise; the gap between the standard rate and the fixed Welcome Rate narrows and can disappear[4][6] |
| September 2022 | End of the period covered by the case[1] |
| Before Nov 2026 | Macquarie pays A$8.8 million to nearly 40,000 customers after complaints[1][2] |
| March 31, 2026 | End of the financial year in which Macquarie fully accounted for the matter[1] |
| November 11, 2026 | ASIC announces the NSW Supreme Court proceeding; Macquarie says it will not contest and expects a A$14 million penalty[1][2] |
| To be set | Court decides whether to approve the proposed penalty[2] |
What it means for Australian savers and banks
For Macquarie, the money is modest next to the size of the group, and it was already set aside. The bigger cost is reputational: Macquarie has built its savings business on a plain, no-conditions account, and Perham himself said customers value that "straightforward" offer.[1]
For the rest of the industry, the message is that ASIC is now watching how savings rates are described, not only whether the maths in the system is right. RMIT finance professor Angel Zhong told The Guardian that promotional offers "get louder" when interest rates move. "That is exactly when clear, honest rate disclosure matters most."[6] It is the second big Australian money story of the week after the Qantas job cuts.
Frequently asked questions
Why is Macquarie Bank being fined A$14 million?
ASIC says Macquarie's website described its savings account Welcome Rate as a "bonus" between December 2021 and September 2022, which could make customers think it was paid on top of the standard rate. It actually replaced the standard rate. Macquarie admits it failed to provide financial services efficiently, honestly and fairly.[1][2]
Is the A$14 million penalty final?
No. It has been jointly proposed by ASIC and Macquarie to the NSW Supreme Court, and the court must approve it.[2]
Am I owed money by Macquarie?
Macquarie says it has already paid A$8.8 million to nearly 40,000 customers. If you opened a Macquarie Savings Account between December 2021 and September 2022 and are unsure whether you were included, contact Macquarie and ask.[1][2]
Does this affect the Macquarie Savings Account today?
The case is about website wording from 2021 and 2022. Macquarie says it has since reviewed its product descriptions. Check the current terms on Macquarie's site for today's rate and any welcome offer.[1]
How do I know if my bank is paying the right savings rate?
Compare the rate on your statement with the rate in your account terms, and check you met every bonus condition that month. If it does not match, ask the bank to explain it.[8]
References
- "Macquarie Bank statement on ASIC proceeding". Macquarie Group. November 11, 2026.
- "Macquarie Bank faces $14m fine over promotion of savings account rates to new customers". Stephanie Chalmers and Nassim Khadem, ABC News. November 11, 2026.
- "Macquarie Bank fined $14 million penalty and must pay $8.8 million in compensation over confusing interest rate descriptions". James Eyers, Australian Financial Review. November 11, 2026.
- "Macquarie Bank to pay $14 million fine after failures in promoting savings accounts". Patrick Brischetto, Nine.com.au. November 11, 2026.
- "Macquarie Bank admits to failures on savings account welcome rate". Finder. November 11, 2026.
- "Macquarie Bank to pay $14m penalty after confusing 'welcome rate' promotion". Jonathan Barrett, The Guardian. November 11, 2026.
- "Macquarie Bank pays $8.8m to 40,000 savings account customers over 'welcome rate' failures". Daniel Newell, The West Australian. November 11, 2026.
- "Aussies warned to check savings account as Macquarie Bank faces $14 million fine over interest promotion". Sophie Venz, Yahoo Finance Australia. November 11, 2026.